By Adam Halioua, founding partner, Goodman Halioua LLP
On July 1, 2026, Ontario made the biggest change to auto insurance accident benefits in years. Many benefits that used to come with every auto policy are now optional coverages that you have to choose to buy. If you’re hurt in a car accident on or after that date, what you can claim now depends much more on the choices made on your policy.
Here is what changed, what didn’t, and what it means for you.
What Is Still Mandatory
Every Ontario auto policy must still include:
- Medical and rehabilitation benefits
- Attendant care benefits
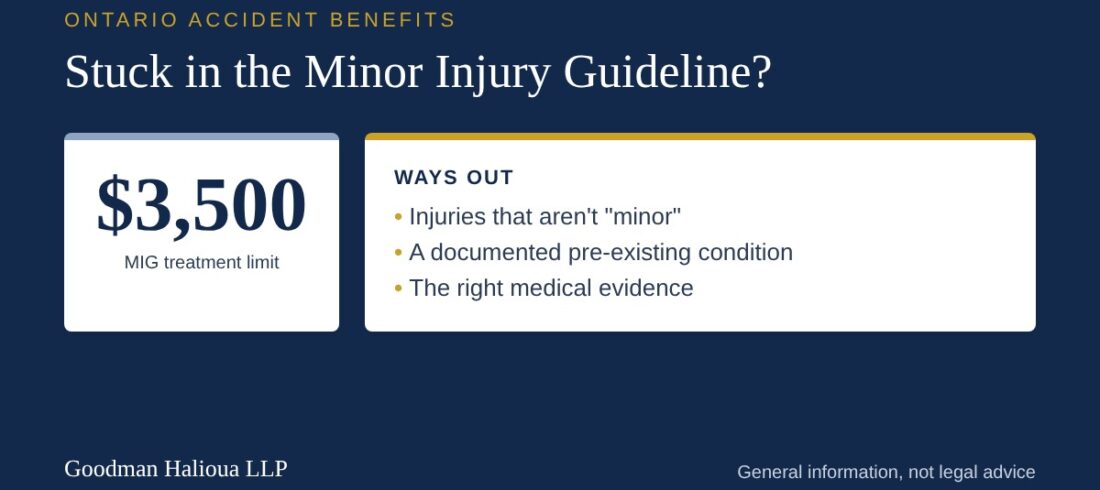
The standard limits for these benefits have not changed: up to $3,500 for minor injuries under the Minor Injury Guideline, up to $65,000 for non-catastrophic injuries, and up to $1,000,000 for catastrophic impairment. Optional coverage can still raise these limits.
What Became Optional
These benefits are now optional. They are only available if they were purchased on the policy that applies to you:
- Income replacement benefits
- Non-earner benefits
- Caregiver benefits
- Housekeeping and home maintenance benefits
- Death and funeral benefits
- Lost educational expenses
- Expenses of visitors
- Damage to clothing, glasses, hearing aids and other personal items
For many people, the most important of these is income replacement. If you work and can’t after a crash, and you didn’t buy income replacement coverage, you may not receive any income replacement benefits from your auto insurer.
Your Auto Insurer Now Pays First for Treatment
Before July 1, 2026, if you had a workplace or private health plan, it usually paid first for treatment, and auto insurance covered what was left. Now, your auto insurer pays first for most medical and rehabilitation costs, with medication as an exception.
This means you no longer need to use up your workplace health benefits before your auto insurer pays. It also means your medical and rehabilitation limit may be used up faster, which matters if your injuries are serious.
Which Accidents and Policies Are Affected
- The new rules apply to accidents on or after July 1, 2026. Accidents before that date are covered by the rules in place at the time.
- Existing policies renew with the same coverage as before unless you or your broker change it. Drivers who choose to remove optional benefits to lower their premium give up that protection.
Passengers, Pedestrians and Cyclists
If you’re hurt as a passenger, pedestrian or cyclist, you usually claim accident benefits from your own auto policy, or the policy of a family member you live with. Whether you have optional benefits, such as income replacement, depends on what that policy includes. If you have no auto policy in your household, different rules apply.
What Hasn’t Changed
- Your right to sue. You can still sue the at-fault driver for pain and suffering, past and future lost income and future care costs, subject to the threshold and the deductible. For people without optional income replacement coverage, the lawsuit may become an even more important source of lost income.
- The deadlines. Tell your insurer within 7 days, return your application (OCF-1) within 30 days of receiving it, and give written notice to the at-fault driver within 120 days. Most lawsuits must start within 2 years.
- Catastrophic impairment. The most seriously injured can still apply to be found catastrophically impaired, which unlocks a higher tier of accident benefits.
- Disputes. Denied accident benefits are still disputed at the Licence Appeal Tribunal, generally within 2 years of the denial.
What You Can Do Now
Before an accident: review your auto policy with your broker or insurer. Ask which optional benefits you have, especially income replacement, and whether the coverage fits your income and family situation. The cheapest premium isn’t always the right choice if you depend on your income.
After an accident:
- Get medical care and keep records.
- Notify your insurer within 7 days.
- Ask your insurer for a copy of your policy and the optional benefits it includes.
- Speak with a lawyer early. When optional benefits aren’t available, other sources of income and care, such as long-term disability, government benefits and a lawsuit, become even more important, and they interact with each other.
Frequently Asked Questions
I was hurt before July 1, 2026. Does this affect me?
Generally, no. Your claim is governed by the rules in place on the date of your accident.
I didn’t buy income replacement coverage. Can I still recover lost income?
Possibly. You may be able to claim lost income in a lawsuit against the at-fault driver, through long-term disability coverage, or through government programs such as EI sickness benefits, CPP Disability or ODSP. We review every possible source at your free consultation.
Does my workplace health plan still pay?
Your auto insurer now pays first for most medical and rehabilitation costs. Your workplace plan may still cover costs above your auto limits or costs your auto policy doesn’t cover.
How do I know what my policy includes?
Check your policy documents or ask your broker or insurer. After an accident, we can help you get and review your policy.
Talk to a Lawyer
Hurt in a car accident after July 1, 2026? The new rules make it more important than ever to understand your coverage early. Our founding partners offer a free, confidential consultation, and we come to you if you can’t come to us.
Book a free consultation | 416-367-4642
This article provides general information, not legal advice. Every situation is different. Contact a lawyer about your specific circumstances.